Gold has certainly glittered recently as it has been one of the best performing assets this year. As of April 30, gold is up 25% year-to-date while most major financial indices are down. Why is gold suddenly performing so well even though inflation is moving back toward the Fed’s 2% target? This edition of Tapping Into Maple will explore the allure of gold and why investors may want to develop a better understanding of the metal.
Gold has served as a means of exchange and store of value for millennia, although it was not always the only form of money. Money is believed to have been invented as a means of exchange in Babylon, one of the world’s wealthiest cities six thousand years ago, but it had no resemblance to what we know as money today. Once coinage came into being around the year 650 B.C., gold and silver were established as the monetary base of the realm. By 550 B.C., the king of Lydia (modern-day Turkey) used gold to mint coins with his image, thus spreading his power and influence. As coins with more reliable weight and purity were minted, these metals gained broad acceptance and formed the basis for most nations’ monetary systems and coinage until relatively recently. Only in 1933 did the U.S. stop minting gold coins (and also making private ownership of gold coins and bullion illegal, only legalizing it again in 1974), and silver coinage production ended in 1964 (technically, it was still used in lesser amounts through 1967).
As a precious metal, gold was revered for its rarity, beauty, and relative ease of storage and transport. It was widely used in jewelry and other adornments for the body and home. Kings and the wealthy used it for tableware and many other household items to display their wealth, and nation-states accepted gold as the global commodity with an established price that could serve as a standard when few standards existed. In fact, the U.S. established an official price of gold at which dollars could be exchanged.
Even after other mediums of exchange became commonly used such as paper money and paper checks, they needed to be backed by gold in order to gain acceptance.
This system ended after the U.S. abandoned the gold standard — in 1933 for domestic transactions and 1971 for international convertibility — and the dollar could no longer be converted into gold. The dollar then became a fiat currency, meaning it simply has value by decree rather than by backing of anything tangible. However, gold remains a widely-used store of value across much of the globe based on its legacy. This is prevalent in relatively undeveloped countries that can exhibit instability or where the legal system is less advanced. Today, central banks and/or treasuries of many nations, including the U.S. Treasury, still own gold in large quantities. Even though the U.S. dollar remains the premier reserve currency, its role has been declining due to a variety of factors, and gold is thought to be the beneficiary as these official buyers add to their holdings.
Cultural norms in some countries such as India, the world’s largest buyer of gold jewelry, are still responsible for a large portion of annual demand for gold. In China, gold is used in many of life’s milestones such as births, weddings, and other milestones. Consumers in less stable or developed nations seek to own gold since it is not linked to the national economy and serves as a more stable store of value. This is particularly true in countries with capital controls that limit how much currency can be invested abroad. The Economist reports that Indian households’ allocation to equities is just 6% compared to 15% for gold. Meanwhile, in countries like China, many of the largest, most lucrative companies are state-owned enterprises and cannot be invested in by individuals. As a result, gold can be a more natural investment vehicle.
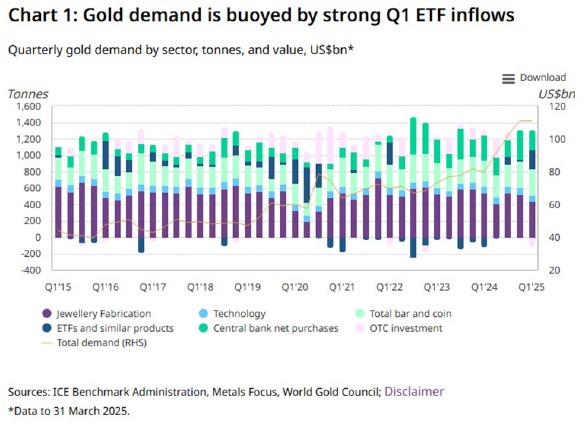
There are some drawbacks to physical ownership of gold such as the need to insure it and store it, which may be prohibitively expensive or inconvenient. Furthermore, gold cannot be traced if stolen in bullion form and is difficult to transport safely in large quantities. ETFs can be used (see chart) which would certainly make it more liquid, but many holders of gold across the less-developed world cannot access a computer and must have physical ownership. Lastly, investors should understand that the ETF does not always own physical gold.
In terms of its acceptability as an investment, there are two schools of thought.
· Adherents of gold as an investment — fondly known as gold bugs — point to its heritage as a medium of exchange and the standard that once backed nations’ currencies. The price of gold has proven to be quite volatile, but there are times when its performance rockets higher due to some global crisis, often a confidence-based crisis where investors question the government’s ability to control inflation or honor its debt. Early 2025 qualifies as this type of crisis with the U.S. involved in a trade war, recasting its position on the global stage as a hegemonic power, while continuing to post massive deficits on top of its $36T in debt.
· Opponents of this view argue that while gold is an asset, it is purely a commodity that has worth because someone says so. Its lack of cash flow in the form of dividends or interest makes it a commodity rather than an investment vehicle. Still, commodities can be used as investment vehicles, but they are considered alternative or non-traditional investments by investment professionals.
Maple Capital’s view is the latter: gold cannot be analyzed or valued based on any observable inputs or metrics such as annual profit, dividends, or interest the way that stocks and bonds are valued. Instead, it is more speculative in nature since its value is derived from others’ willingness to pay a higher price in the future without the benefit of a stream of future cash flows.
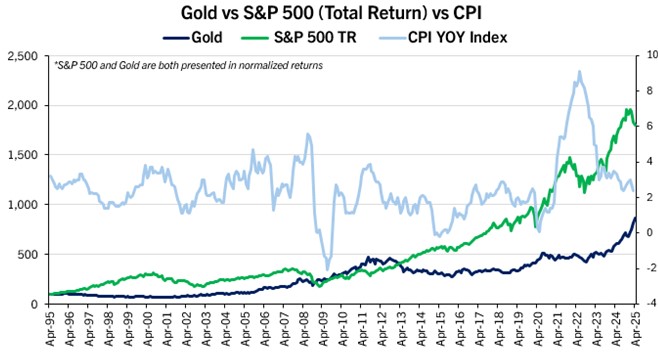
As shown in the chart, gold has been highly volatile over recent decades. At times, its performance is flat or negative, even during inflationary times. As a Barron’s article recently stated, “gold has been a so-so inflation hedge over the past 50 years, and at times a disappointing one.” One need only look at its performance in 2022 during the global pandemic, when inflation surged, to see this weak track record firsthand.
In summary, we hope you have enjoyed this narrative on gold’s illustrious history as a highly desired metal. After its strong run-up in price this year, gold may not be an attractive investment at this juncture. After all, past performance is no guarantee of future results! That said, as geopolitical polarization continues to incentivize central banks to diversify away from the dollar, gold bugs may find that its glitter will only get brighter.
Firm Definition and Contact Information
Maple Capital Management, Inc. (MCM) is an independent SEC Registered Investment Advisor with offices in Montpelier, Vermont and Atlanta, Georgia.
This commentary reflects the views of MCM and should not be considered to be investment or financial advice. MCM does not warranty these views and will not update this communication after the date of publication. Any mention of specific securities is done for illustrative purposes and the securities mentioned may or may not be held in client accounts. No assumption or assurance should be taken that securities mentioned will be safe or profitable investments. Past performance is not indicative of future results
For further information, please contact David Bosworth at 1-802-229-2838 or at [email protected]. For further information about Maple Capital, including a copy of our informational brochure, please visit our website at www.maplecapital.com.
Disclaimer
This document is a general communication being provided for informational purposes only. It is educational in nature and not designed to be taken as advice or a recommendation for any specific investment product, strategy, plan feature or other purpose in any jurisdiction. This material does not contain sufficient information to support an investment decision and it should not be relied upon by you in evaluating the merits of investing in any securities or products. In addition, users should make an independent assessment of the legal, regulatory, tax, credit, and accounting implications and determine, together with their own financial professional, if any investment mentioned herein is believed to be appropriate to their financial situation and investment profile. Investors should ensure that they obtain all available relevant information before making any investment. It should be noted that investments involve risks, the value of investments and the income from them may fluctuate in accordance with market conditions and taxation agreements and investors may not get back the full amount invested. Both past performance and yields are not reliable indicators of current and future results. All information presented herein is considered to be accurate at the time of production, but no warranty of accuracy is given and no liability in respect of any error or omission is accepted.
Past performance does not guarantee future results. Diversification does not guarantee investment returns and does not eliminate the risk of loss.