as of 7.31.2025
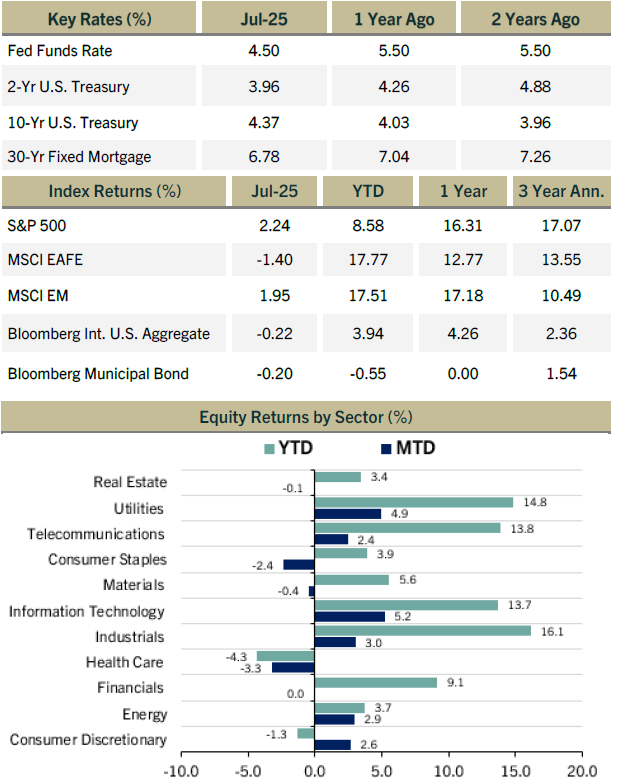
- Equity markets enjoyed another solid month of gains in July, boosted by positive earnings surprises from several key companies. The leading sector was technology followed by the more boring utilities sector, which is benefiting from demand for more electricity due to the AI-driven boom from data centers.
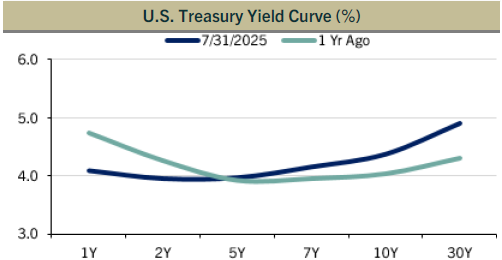
- Fixed income total returns were mostly negative: -0.22% for the Bloomberg U.S. Intermediate Aggregate Index and -0.20% for the Municipal Bond Index. Bond yields have been in a relatively narrow trading range and headed slightly higher after the Fed ended its meeting with a less dovish message than had been expected.
- Once again, the Fed’s Federal Open Market Committee (FOMC) maintained its “wait-and-see” approach, preferring to keep its short term federal funds rate unchanged as they assess the impact of the Trump administration’s trade policies. However, they still project two rate cuts by year-end.
- Second quarter GDP came in at 3.0% annualized, which on the surface appears better than expected. Looking a bit deeper, the same factors that distorted first quarter GDP were responsible for the exaggerated strength. Imports came in very heavy in the first quarter as businesses built inventory ahead of tariff increases, while the opposite occurred in the second quarter. A better measure of underlying growth, real final sales to private purchasers, grew at 1.9% in the first quarter and 1.2% in the second.
- Despite the fact that several tariff deals were announced during the month, uncertainty on tariff policy remains high. One example is the tariff on copper imports, which Trump warned about in early July, threatening one as high as 50%. Copper is used in a wide variety of products including smartphones, appliances, power grids, and automobiles. U.S. copper prices surged to record highs on this announcement. On July 30, the policy was changed to exclude unprocessed copper and instead would only apply to refined copper. This abrupt change resulted in the largest intraday drop on record in copper futures prices.
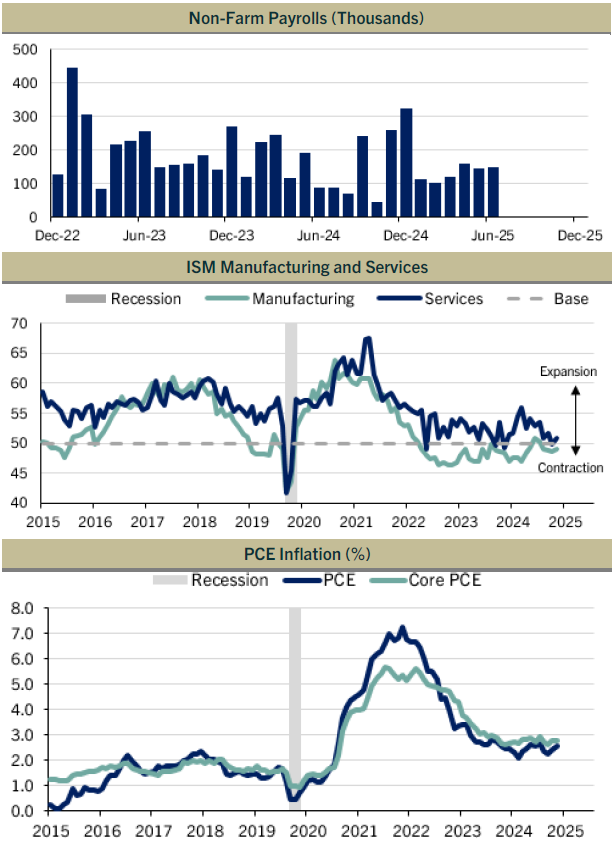
- Despite calls for Fed rate cuts, the latest readings on inflation point to persistent results above the 2% target. June’s core PCE deflator was 2.8% year-over-year, and the monthly figure reflected a 0.5% spike in durable goods. This appears to be one of the first clear signs of tariff-induced inflation on the goods side, although services prices, which remain free of this influence, are slowly abating.
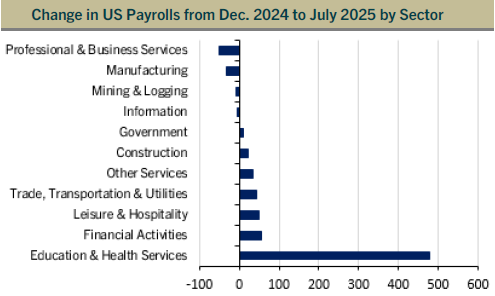
- Although most economic data have remained resilient, the labor market does appear to be weakening more broadly despite relatively tame weekly unemployment claims. The labor force participation rate has been steadily declining this year, from 62.6% in January to 62.2% in July, owing to tighter immigration policy and an aging workforce. Moreover, job gains from the monthly payroll reports have been very concentrated in the healthcare and social services segments, while more cyclical areas such as manufacturing and mining have been stagnant or in decline.
- If the labor market deterioration warrants a Fed rate cut but the inflation data is moving in the opposite direction, the Fed will have quite a quandary at its next meeting in September. The Fed’s dual mandate requires them to consider both unemployment and price stability. How far from target each of the objectives are will be the determining factor in deciding the best course of action.
- With nearly two thirds of the S&P 500 index having reported second quarter earnings, 82% are reporting positive surprises compared to consensus estimates. The overall average earnings gain stands at 9.1%, well above what the market had expected.
- The U.S. dollar strengthened in July for the first time this year, but it remains nearly 8% lower on a year-to-date basis.
- Nvidia Corp., Microsoft Corp., and Amazon.com Inc. were the top three contributors in the S&P 500 in July, while Netflix Inc., UnitedHealth Group Inc., and IBM Corp. were the biggest detractors.
Firm Definition and Contact Information
Maple Capital Management, Inc. (MCM) is an independent SEC Registered Investment Advisor with offices in Montpelier, Vermont and Atlanta, Georgia.
This commentary reflects the views of MCM and should not be considered to be investment or financial advice. MCM does not warranty these views and will not update this communication after the date of publication. Any mention of specific securities is done for illustrative purposes and the securities mentioned may or may not be held in client accounts. No assumption or assurance should be taken that securities mentioned will be safe or profitable investments. Past performance is not indicative of future results
For further information, please contact David Bosworth at 1-802-229-2838 or at [email protected]. For further information about Maple Capital, including a copy of our informational brochure, please visit our website at www.maplecapital.com.
Index Definitions
The S&P 500 (S&P 500) Total Return is a market capitalization-weighted index composed of the 500 most widely held stocks whose assets and/or revenues are based in the US; it’s often used as a proxy for the U.S. stock market. TR (Total Return) indexes include daily reinvestment of dividends.
MSCI EAFE Total Return Net is the Morgan Stanley Capital International Europe, Australia, and Far East index that is a market-capitalization-weighted index of 21 non-U.S. industrialized country indexes. The index includes net dividends reinvested minus-tax-credit calculations, but subtracts withholding taxes retained at the source for foreigners who do not benefit from a double taxation treaty.
The MSCI Emerging Markets (MSCI EM) Index captures large and mid cap representation across 27 Emerging Markets (EM) countries.
Bloomberg Municipal Bond Index Total Return Index Value Unhedged USD (Municipal Bond Index) covers the US-denominated long-term tax exempt bond market. The index has four main sectors: state and local general obligation bonds, revenue bonds, insured bonds and prerefunded bonds.
The Bloomberg Intermediate U.S. Aggregate Bond Index is a broad-based flagship benchmark that measures the performance of investment grade, U.S. dollar-denominated, fixed-rate taxable bond market with less than 10 years to maturity. The securitized sector includes Treasuries, government-related and corporate securities, MBS (agency fixed-rate and hybrid ARM pass-throughs), ABS, and CMBS.
The federal funds rate is the interest rate at which depository institutions trade federal funds (balances held at Federal Reserve Banks) with each other overnight. When a depository institution has surplus balances in its reserve account, it lends to other banks in need of larger balances. In simpler terms, a bank with excess cash, which is often referred to as liquidity, will lend to another bank that needs to quickly raise liquidity. (1) The rate that the borrowing institution pays to the lending institution is determined between the two banks; the weighted average rate for all of these types of negotiations is called the effective federal funds rate.(2) The effective federal funds rate is essentially determined by the market but is influenced by the Federal Reserve through open market operations to reach the federal funds rate target. All Key Rates and Returns by Index are quoted out of Bloomberg.
The CPI Index represents changes in prices of all goods and services purchases for consumption by urban households. Retail Gas Prices are provided by AAA using data from up to 120,000 retail stations. West Texas Intermediate (WTI) crude oil is a specific grade of crude oil and one of the main three benchmarks in oil pricing, along with Brent and Dubai Crude.
Equity Returns by Sector are based on the GICS methodology. Return data are calculated by Bloomberg using constituents and weights as provided by Standard & Poor’s. Returns are cumulative total return for stated period, including reinvestment of dividends.
Chart Definitions
The Services and Manufacturing PMI from the Institute for Supply Management (ISM) is a composite index based on the diffusion indexes for four of the indicators with equal weights: Business Activity (seasonally adjusted), New Orders (seasonally adjusted), Employment (seasonally adjusted) and Supplier Deliveries. The Manufacturing PMI is a composite index based on the diffusion indexes of five of the indexes with equal weights: New Orders (seasonally adjusted), Production (seasonally adjusted), Employment (seasonally adjusted), Supplier Deliveries, and Inventories (seasonally adjusted). Diffusion indexes have the properties of leading indicators and are convenient summary measures showing the prevailing direction of change and the scope of change. An index reading above 50 percent indicates that the services economy is generally expanding; below 50 percent indicates that it is generally declining. Supplier Deliveries is an exception. A Supplier Deliveries Index above 50 percent indicates slower deliveries and below 50 percent indicates faster deliveries.
The PCE Price Index Excluding Food and Energy, also known as the core PCE price index, is released as part of the monthly Personal Income and Outlays report. The core index makes it easier to see the underlying inflation trend by excluding two categories – food and energy – where prices tend to swing up and down more dramatically and more often than other prices. The core PCE price index is closely watched by the Federal Reserve as it conducts monetary policy. The PCE price index, released each month in the Personal Income and Outlays report, reflects changes in the prices of goods and services purchased by consumers in the United States. Quarterly and annual data are included in the GDP release.
Total Nonfarm, commonly known as Total Nonfarm Payroll, is a measure of the number of U.S. workers in the economy that excludes proprietors, private household employees, unpaid volunteers, farm employees, and the unincorporated self-employed. This measure accounts for approximately 80 percent of the workers who contribute to Gross Domestic Product (GDP).
The diffusion non-farm payrolls chart are based on the percent of industries with employment increasing plus one-half the industries unchanged employment, where 50% indicates an equal balance between industries with increasing and decreasing employment.
Disclaimer
This document is a general communication being provided for informational purposes only. It is educational in nature and not designed to be taken as advice or a recommendation for any specific investment product, strategy, plan feature or other purpose in any jurisdiction. This material does not contain sufficient information to support an investment decision and it should not be relied upon by you in evaluating the merits of investing in any securities or products. In addition, users should make an independent assessment of the legal, regulatory, tax, credit, and accounting implications and determine, together with their own financial professional, if any investment mentioned herein is believed to be appropriate to their financial situation and investment profile. Investors should ensure that they obtain all available relevant information before making any investment. It should be noted that investments involve risks, the value of investments and the income from them may fluctuate in accordance with market conditions and taxation agreements and investors may not get back the full amount invested. Both past performance and yields are not reliable indicators of current and future results. All information presented herein is considered to be accurate at the time of production, but no warranty of accuracy is given and no liability in respect of any error or omission is accepted.
Past performance does not guarantee future results. Diversification does not guarantee investment returns and does not eliminate the risk of loss.
www.maplecapital.com | 535 Stone Cutters Way, Montpelier, VT 05602 | Toll Free: 800.255.9946